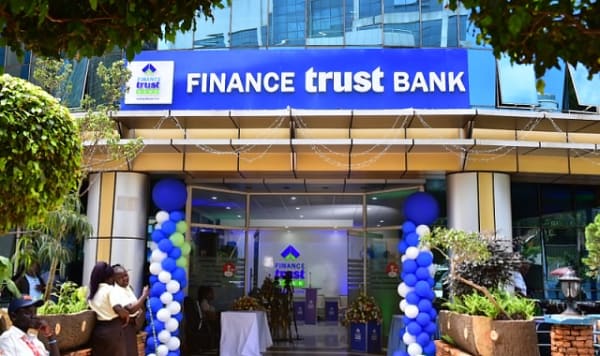
Finance Trust Bank (FTB) is set to relinquish its Tier I commercial banking licence and operate as a Tier II credit institution beginning 1 April 2026, following approval by the Bank of Uganda (BoU).
The decision marks a strategic realignment for one of Uganda’s long-standing indigenous financial institutions.
According to BoU, the transition follows a three-month adjustment period running from 1 January to 31 March 2026, during which the bank will gradually discontinue products and services that are exclusive to commercial banks. The regulator said the phased approach is intended to minimise disruption to customers and safeguard the stability of the financial system.
The downgrade was initiated by Finance Trust Bank’s board of directors as part of a broader repositioning exercise aimed at serving its core clientele more efficiently. BoU noted that FTB meets the minimum capital requirements for a credit institution licence and remains adequately capitalised under the new regulatory category.
Finance Trust Bank’s journey spans more than four decades. The institution was founded in 1984 as Uganda Women’s Finance and Credit Trust, a non-governmental organisation created to extend financial services to low-income earners, particularly women who were largely excluded from the formal banking system at the time.
In 1997, it transitioned into Uganda Women’s Finance Trust Limited, and by 2005 it had secured a licence as a microfinance deposit-taking institution (MDI). Continued growth and expansion paved the way for a major milestone in 2013, when the Bank of Uganda granted it a full commercial banking licence, officially rebranding it as Finance Trust Bank. Since then, the bank has operated a nationwide branch network with a strong focus on inclusive banking.
Uganda’s financial system is organised into four regulatory tiers. Tier I commercial banks offer the widest range of services, including cheque accounts, foreign exchange trading, international transactions and interbank operations, but they are subject to the highest capital requirements.
Tier II credit institutions, such as the licence FTB is moving to, are allowed to take deposits and issue loans but operate with a narrower product range and lower capital thresholds. Tier III institutions are microfinance deposit-taking entities, while Tier IV comprises non-deposit-taking microfinance firms and savings and credit cooperatives (SACCOs).
In recent years, rising capital requirements have prompted several banks to step down from Tier I to Tier II status. Finance Trust Bank’s move reflects this broader trend, signalling a return to a model more closely aligned with its historical roots in community-focused and inclusive finance.